

First Time Home Buyers
Buying Your First Home in Northern Colorado
Buying your first home can feel overwhelming, but it does not have to be.
Whether you are wondering how much money you need, what credit score is required, whether you qualify for down payment assistance, or what your monthly payment might look like, I can help you understand the process from the beginning.
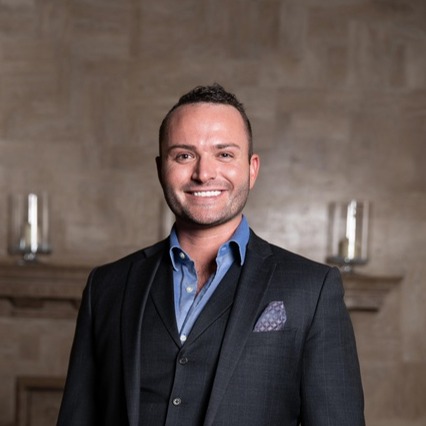
I am Chad Nixon with The Nixon Team at RE/MAX Alliance, and I help first time home buyers throughout Greeley, Fort Collins, Windsor, Loveland, Johnstown, Evans and the surrounding Northern Colorado communities.
You do not need to know everything before reaching out. In fact, one of the best times to talk with me is before you think you are completely ready.
Start Your Home Buying Plan See Homes for Sale in Northern Colorado
How Much Money Do You Need to Buy Your First Home?
One of the biggest misconceptions about buying a home is that you need a 20 percent down payment. Many buyers do not.
Depending on the loan program and your qualifications, you may be able to purchase a home with a relatively small down payment, and some buyers may qualify for programs requiring little or even no down payment.
Common options can include:
- Conventional loans with down payments starting around 3 percent for qualified buyers.
- FHA loans that may allow approximately 3.5 percent down for qualified borrowers.
- VA loans that may offer zero down payment for eligible veterans and service members.
- USDA loans that may provide zero down financing on eligible homes and for qualified buyers in certain rural or suburban areas.
- Colorado down payment assistance programs, including CHFA programs that may help eligible buyers reduce the amount of cash needed at closing.
Program requirements, interest rates and eligibility can change, so buyers should speak with a qualified lender to determine which options are currently available. For a deeper breakdown of cash to close, see How Much Do You Need to Buy a Home in Northern Colorado.
You may be closer to buying a home than you think.
Colorado First Time Home Buyer Assistance
First time buyers in Colorado may have access to programs designed to make homeownership more affordable. Depending on income, credit, property location and the loan program, assistance may be available toward a down payment or closing costs.
CHFA (Colorado Housing and Finance Authority) is one of the programs lenders here use often. Some CHFA options may help with down payment or closing costs. Many of those programs still require a minimum borrower contribution of $1,000, which may come from an eligible gift. Program, income, credit and property requirements apply.
Programs can change over time, which is why I recommend starting with a conversation rather than assuming you will or will not qualify. I can connect you with experienced Northern Colorado lenders who regularly work with first time home buyers and can explain the programs currently available. I do not guarantee qualification or a specific assistance amount.
What Credit Score Do You Need to Buy a House?
There is no single credit score required for every home buyer. The minimum can vary depending on the type of mortgage, lender guidelines, debt levels, income and other factors.
You do not need perfect credit to start the conversation. Even if your credit is not where you want it to be today, it can still be worth talking with a lender. Sometimes relatively small changes can improve your financing options.
What Does It Cost to Work With a Buyer Agent?
Many buyers are concerned that hiring a REALTOR will mean another large out of pocket expense.
In most transactions, we negotiate for the seller to cover the buyer agent’s commission, so buyers typically do not pay it out of pocket. We’ll handle the details and explain everything upfront, so you can move forward confidently without any surprises.
Compensation is addressed in the buyer agreement and discussed with you before we begin, so you will understand exactly how it works before making any decisions. Buyer representation is not always free. My goal is to make the process clear and help you structure the strongest overall purchase possible.
First Time Home Buying Process
1. Talk With Me
We start with a simple conversation about your goals, timeline, preferred locations and what you would like your monthly payment to look like.
2. Get Preapproved
A lender reviews your income, credit, debts and available funds and helps determine a comfortable price range.
3. Build Your Home Search
We narrow down neighborhoods, property types, price ranges and features that matter most to you.
4. Tour Homes
I help you compare homes and look beyond cosmetic features to things that can affect long term value and ownership costs.
5. Write the Offer
I help structure and negotiate the offer based on the property, current market conditions and your priorities.
6. Inspection and Due Diligence
After going under contract, we work through inspections, disclosures, title, financing, appraisal and any appropriate negotiations.
7. Final Walkthrough and Closing
Once everything is complete, you sign the final documents and receive the keys to your first home.
How Much House Can I Afford?
Affordability is about more than the maximum loan approval. A comfortable monthly payment also has to leave room for the rest of your life.
We look at the monthly mortgage payment, property taxes, homeowners insurance, HOA dues when they apply, utilities, maintenance, existing monthly debt, emergency savings, and how you actually want to live.
I would rather help you buy a home that fits your life than simply focus on the maximum amount a lender may approve.
Should I Buy Now or Keep Renting?
Renting can make sense for some people, while homeownership may make sense for others. There is no single right answer.
Factors include how long you expect to stay in the area, your current rent, your estimated mortgage payment, available savings, job stability, home prices, interest rates and long term goals.
If you are unsure, I can help you compare the numbers and look at actual homes in your price range before you make the decision.
Where Should First Time Buyers Look in Northern Colorado?
Buyers looking for a lower price point often start in different communities than buyers who want a short commute, newer construction, acreage or a specific downtown. I will match the search to your budget and daily life, not a one size list.
Greeley is my home base and a common first stop. Evans sits next door. Fort Collins and Windsor draw buyers who want those specific towns. Loveland, Johnstown, Milliken, Eaton, Severance and Timnath each have a different mix of resale, new construction and commute. See the Northern Colorado communities directory and the Fort Collins vs Greeley vs Windsor guide if you are still comparing.
More on the process: Buying a Home in Greeley and Buying a Home in Fort Collins.
New Construction for First Time Buyers
First time home buyers should consider both resale homes and new construction. Builders often have their own sales representatives on site. Having your own buyer agent still matters. I represent you, not the builder, when we tour a new community, compare incentives and write the contract.
Builder incentives can sometimes include interest rate incentives, closing cost assistance or upgrades, depending on the builder and current promotion. Availability and incentives change. I will check what is actually being offered on the communities you like.
What About Zero Down Home Loans?
Zero down financing does exist for some qualified buyers. Eligible VA borrowers and some USDA buyers may purchase with no down payment. Property location and buyer eligibility matter. USDA is limited to certain areas and income limits. Not every buyer and not every home will qualify. Do not assume you can or cannot buy with zero down until a lender looks at your situation.
Do I Need Thousands of Dollars for Closing Costs?
Closing costs are separate from a down payment. They can include lender charges, title related expenses, prepaid taxes, insurance and other transaction costs. The amount depends on the loan, the property and the closing date.
Depending on the transaction, we may be able to negotiate seller concessions toward eligible closing costs. Seller concessions are not guaranteed. They depend on the market, the home and the rest of the offer.
Common First Time Home Buyer Mistakes
- Waiting until you have 20 percent down before asking questions
- Shopping for homes before understanding financing
- Opening new credit accounts during the home buying process
- Making large unexplained bank deposits
- Buying a car before closing
- Focusing only on the purchase price instead of the monthly payment
- Skipping inspections simply to make an offer more competitive
- Assuming new construction does not require representation
- Trying to time the market perfectly
- Assuming you will not qualify without speaking to a lender
Why Work With Chad Nixon?
Buying your first home is a major financial decision, and you should have someone on your side who will explain the process instead of assuming you already understand it.
I have spent more than a decade in real estate and help buyers throughout Northern Colorado understand the market, evaluate homes, negotiate offers and work through the details between the first conversation and closing day. I am based in Greeley with The Nixon Team at RE/MAX Alliance. My license number is FA100047347.
I can connect you with trusted local lenders and other real estate professionals. You are working with me directly.
My job is not to pressure you into buying a home. My job is to help you make a smart decision when the right opportunity comes along. Learn more about Chad. Eligible military, first responder, teacher and healthcare buyers can also look at Nixon for Heroes.
First Time Home Buyer FAQ
How much money does a first time home buyer need in Colorado?
You may need less than you think. Some conventional loans allow as little as 3% down, FHA loans typically require 3.5%, and eligible VA or USDA buyers may qualify for 0% down. Colorado buyers may also qualify for CHFA down payment or closing cost assistance, with a minimum borrower contribution of $1,000, which may come from an eligible gift. Program, income, credit and property requirements apply. We can connect you with a trusted lender to explore your options and determine what works best for you.
Do first time home buyers need 20 percent down?
No. Many qualified buyers purchase with much less than 20 percent down. Twenty percent can reduce some loan costs, but it is not required for every loan.
Are there first time home buyer programs in Colorado?
Yes. Options can include low down payment loans and down payment or closing cost assistance. CHFA is one program lenders in Colorado use. Eligibility depends on income, credit, the property and the loan. I can connect you with a lender who works with these programs.
What is CHFA?
CHFA is the Colorado Housing and Finance Authority. It offers loan and assistance programs that may help eligible buyers with a down payment or closing costs. Requirements change, and not every buyer qualifies.
What credit score does a first time home buyer need?
There is no one score for every loan. Lender guidelines, loan type, income and debts all matter. Talk with a lender before you assume your score is too low.
Is a real estate agent’s help free for buyers?
In most transactions, we negotiate for the seller to cover the buyer agent’s commission, so buyers typically do not pay it out of pocket. We’ll handle the details and explain everything upfront, so you can move forward confidently without any surprises.
Can a seller pay my buyer agent compensation?
In many transactions we can request that the seller contribute toward the buyer broker compensation as part of the offer. It is discussed in the buyer agreement before we start. It is not automatic in every deal.
Can a seller pay my closing costs?
Sometimes. We may negotiate seller concessions toward eligible closing costs. It depends on the home, the market and lending rules. It is not guaranteed.
How much are closing costs for a first time buyer?
Closing costs are separate from the down payment and vary by loan, property and closing date. A lender can estimate them once you are preapproved. I will also walk through a sample cash to close before you write an offer.
Should I get preapproved before looking at houses?
Yes. Preapproval tells you a realistic price range and shows sellers you can finance the purchase. You can still talk with me before you are preapproved.
Can I buy a home if I have student loans?
Often yes. Lenders count student loan payments in your debt to income ratio. A lender can tell you how your loans affect a preapproval.
Can I buy a home if I have credit card debt?
Often yes, depending on the balances, payments and the rest of your file. Do not open new cards or move large balances around without asking the lender first.
Is Greeley a good place for first time home buyers?
Greeley is where I am based, and many first time buyers start here because it offers a wide mix of resale homes, new construction and nearby Evans. Compare it with Fort Collins, Windsor and Loveland based on commute, price range and the kind of home you want, not a slogan.
Is Northern Colorado affordable for first time home buyers?
It depends on the city, the home type and your loan. Prices and inventory change. I would rather look at actual listings in your range than guess from a headline.
Is new construction good for first time home buyers?
It can be, especially if you want a newer home and current builder incentives. Have your own agent. Incentives and availability change.
Should I buy a home now or wait for interest rates to fall?
Rates, prices and your own timeline all move. Waiting can help or hurt depending on what homes cost later and how long you stay. If you are unsure, we can compare rent versus a real payment on homes you could buy today.
How long does it take to buy a house?
It depends on financing, inspection and the contract. Many financed purchases close several weeks after the offer is accepted. I will map your timeline once we know your loan type.
What is the first thing I should do if I want to buy a house?
Talk with me, then get preapproved. You do not need to have a house picked out first.
Can I talk with a REALTOR even if I am not ready to buy yet?
Yes. One of the best times to call is before you think you are ready. We can build a plan for next month or next year.
Chad is not a lender. Loan programs, assistance, credit guidelines and closing costs change. A qualified lender must confirm what you qualify for.
Thinking About Buying Your First Home?
You do not need to have everything figured out before reaching out. Whether you want to buy in the next month, six months, or simply want to understand what you would need to do to become ready, I am happy to help you build a plan.
Chad Nixon
The Nixon Team at RE/MAX Alliance
Northern Colorado REALTOR
Call or text 970-776-0658 or email chad@thenixonteam.com.
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than The Nixon Team are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 21, 2026 9:45 PM UTCd
 Information deemed reliable but not guaranteed by the MLS. © 2026 Information and Real Estate Services, LLC.
Information source: Information and Real Estate Services, LLC. Provided for limited non-commercial use only under IRES Rules. © Copyright IRES.
The information being provided is for the consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing.
The IRES, LLC Data on this
